Detect scams by seeing the relationship between sender and receiver.
Incognia combines physical social graph evidence from trusted locations and persistent device recognition with additional scam intelligence signals to uncover suspicious relationships and help banks stop scams before money moves.
Good fraud controls can still miss an authorized scam.
Who is making the payment?
Does the payment look unusual?
What connects both parties?
See who is getting paid,
not just who's paying.
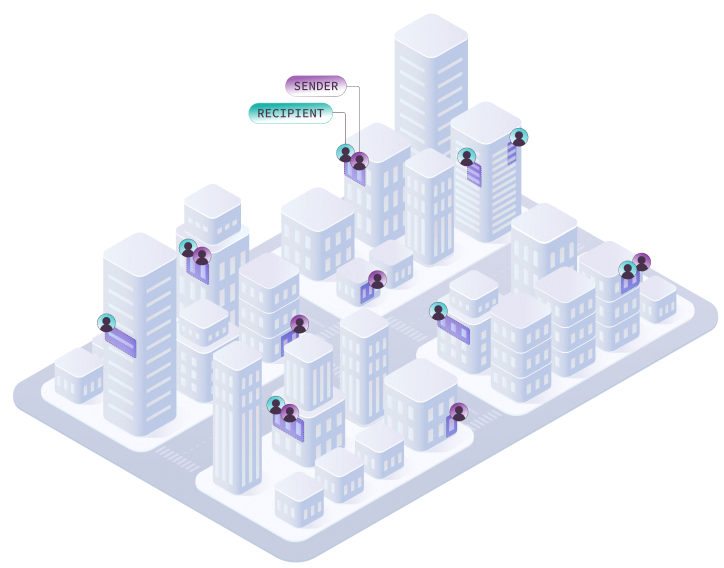
Incognia's physical social graph uses historical trusted locations to surface evidence indicative of relationships between sender and recipient.
- Shared Frequent Locations Repeated visits to the same precise places can provide evidence of an established real-world relationship.
- Patterns beyond distance historical locations Compare where both parties habitually spend time with apartment-level precision, not their GPS or IP distance at the moment of payment.
- Supporting scam intelligence signals corroboration Use available mule-account, active-call, remote-access and device-integrity signals to strengthen or challenge the relationship assessment.
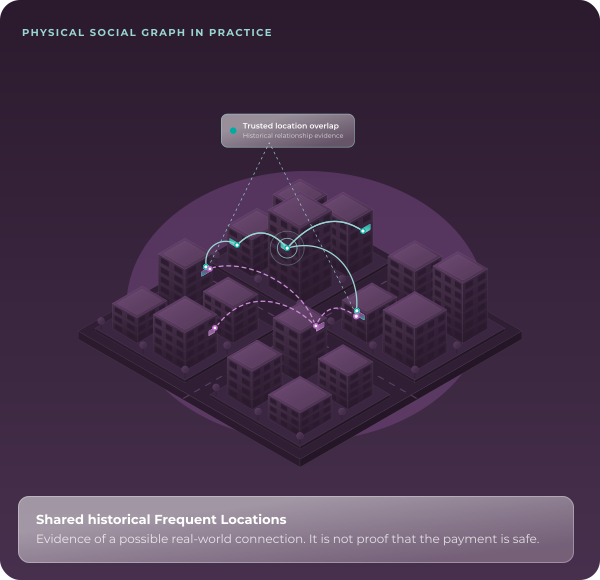
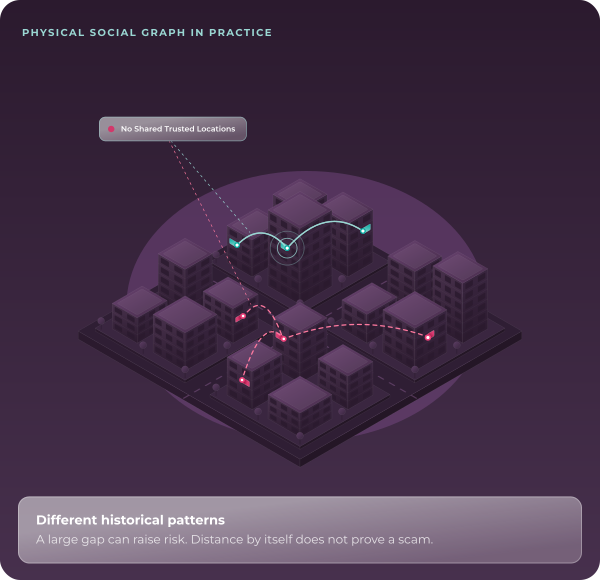
Patented Trusted Locations.
The foundation of Incognia's Physical Social Graph.
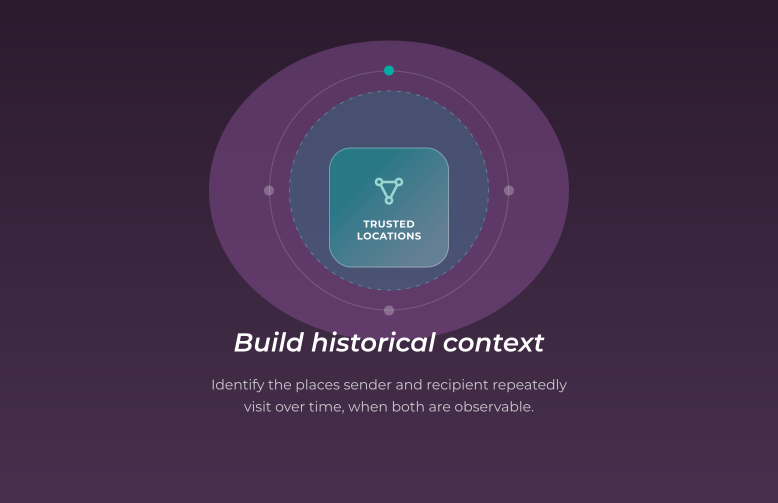
Incognia builds persistent context from the places both parties frequent, rather than relying on the sender's location during the payment.
That historical evidence helps uncover real-world connections and suspicious relationship patterns that do not appear in a transaction record.
- Historical relationship intelligence Identify shared trusted locations and recurring patterns that provide evidence of real-world connections between sender and recipient.
- Cross-party intelligence Use intelligence across participating institutions to uncover suspicious connections beyond a bank's own transaction history.
- A broader network view Relevant relationship and abuse evidence can extend beyond a bank's own transaction history.
Relationship history can expose scams that look legitimate.
Trusted Locations alone identified approximately 70% of scam transactions in one analyzed dataset, before layering in other validation signals.
Not a universal detection rate. Additional risk signals corroborate the relationship evidence.
of scam transactions identified
From authorized payment to informed scam decision.
What banks
should know.
Is this the customer's location at payment time?
No. Incognia compares the sender's and receiver's historical Frequent Locations: the places they repeatedly visit over time. It does not treat momentary proximity as proof of a relationship.
Does a large distance or no shared location prove fraud?
No. People legitimately pay distant recipients every day. Historical relationship evidence is combined with other available scam indicators to assess risk, not used as a standalone fraud verdict.
Does the analysis require data on both sender and recipient?
Full sender-receiver relationship analysis depends on having relevant intelligence about both parties. Signal availability depends on network coverage and observable history.
How does it work with existing fraud controls?
Incognia contributes cross-party relationship evidence alongside supporting indicators such as active-call, remote-access and device-integrity signals. The bank applies these assessments within its existing fraud policies.
Does Incognia block the transfer?
Incognia returns risk evidence; the bank decides whether to authorize, step up, decline or investigate the payment.
Detect scams that pass authentication. Before funds move.
- Discuss authorized-payment scam scenarios
- Explore historical relationship and supporting risk signals
- Review fit with your existing payment decisioning